

Hungary’s commercial real estate investment volume exceeded €460 million in the first half of 2026, up 57% year-on-year, according to CBRE’s latest comprehensive market report, The View 16.
CBRE now expects full-year investment volume of €900 million to €1 billion, which would be the highest annual level since 2022. Around €450 million of additional transactions were already under offer or in advanced negotiations when the report was prepared.
Retail leads with €195 million in investment
Retail was the largest investment sector in the first half, generating approximately €195 million in transactions after years of relatively limited activity. CBRE counted 102 new store openings in Hungary during H1 2026. The share of international retailers’ new openings across CEE increased to 13%, compared with 8%-10% in previous years.
Vacancy remains very low in the most sought-after retail locations, while prime rents have increased. On Budapest’s Fashion Street, CBRE puts rents at approximately €170-€200 per sqm per month.
Second quarter alone generated around €150 million across six deals, with offices representing 44% of quarterly volume, industrial assets 37% and retail 12 percent.
Industrial stock reaches 6.5 million sqm
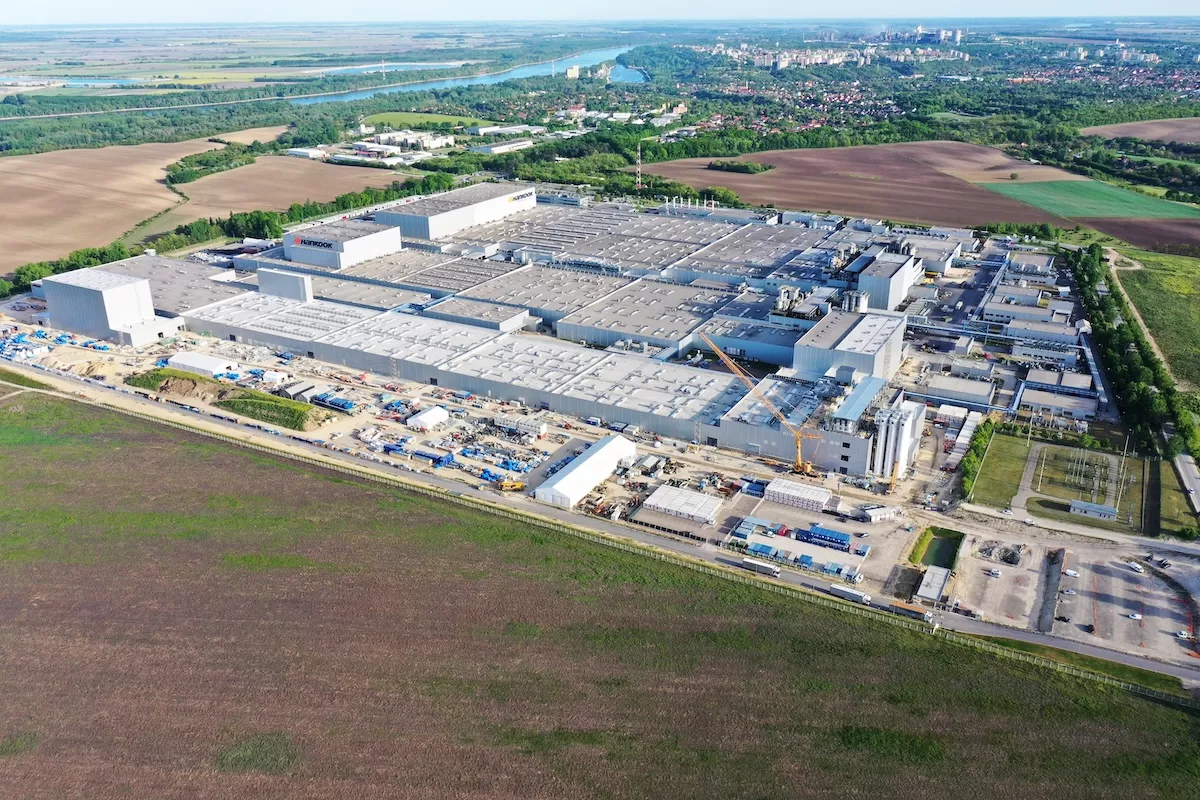
Hungary’s modern industrial and logistics stock increased to 6.5 million sqm, while leasing activity was 13% higher year-on-year in the first half. Kecskemét, Debrecen and Győr are the main regional demand centres, supported by automotive and manufacturing investments.
The difference between Budapest and regional markets remains significant. Vacancy in the Budapest agglomeration reached 14.8%, while the regional vacancy rate fell to 10.5%. Pre-leasing rates for properties under construction stood at 55% around Budapest and 58% in regional markets.
CBRE’s Q2 industrial figures show that another 118,000 sqm was completed during the quarter across five buildings, while more than 500,000 sqm remained under construction nationwide.
Budapest has 480,000 sqm of offices under development
Budapest’s office development pipeline has also increased substantially. The under development pipeline sits at approximately 480,000 sqm, with almost 80% already covered by pre-lease agreements.
Based on announced projects, as much as 322,000 sqm of new office space could be delivered during 2026, although the timing of several projects remains uncertain. CBRE’s dedicated Q2 office report recorded 215,000 sqm of leasing activity during H1, broadly unchanged year-on-year. However, 53% of transactions were lease renewals and net take-up declined 19%.
Office vacancy stood at 12.2%, 0.6 percentage points below the previous year, while prime headline rents remained at €25.5 per sqm per month. New pipeline projects are generally marketed at €20-€25 per sqm per month.
Nno new offices were completed during the second quarter and that some expected 2026 deliveries have been delayed, particularly projects involving public-sector occupancy.
Budapest hotel rates rise to €114
The hotel market continued to expand during the first six months of the year, with 10.9 million guest nights, up 4.2% year-on-year. In Budapest, the average daily hotel room rate increased to €114, while revenue per available room, or RevPAR, reached €78.